The IRS considers gambling winnings taxable income regardless of whether anyone reports them to you. This fundamental principle creates obligations that many recreational gamblers overlook until receiving unexpected tax documents or facing audit inquiries. Understanding federal and state tax treatment of gambling income, maintaining proper records, and correctly reporting winnings and losses helps you stay compliant while potentially reducing your tax burden through legitimate deductions.
Casino sportsbooks operating under state licenses report substantial winnings directly to the IRS, meaning the government already knows about many of your wins before you file. Attempting to hide reported winnings invites audit attention and potential penalties. The better approach involves understanding what triggers reporting, documenting your gambling activity thoroughly, and claiming all legitimate deductions to minimize the taxes you actually owe on your net gambling results.
Federal Tax Treatment of Gambling Winnings
All gambling winnings constitute taxable income under federal law. This includes sportsbook wins, casino game profits, poker tournament prizes, lottery winnings, and any other gambling proceeds. The form of winning doesn’t matter — cash, prizes, comps with monetary value — it’s all taxable.
Gambling winnings are taxed as ordinary income at your marginal tax rate. Unlike capital gains that might receive preferential treatment, gambling income simply adds to your regular income and is taxed accordingly. A $10,000 gambling win for someone in the 22% bracket adds $2,200 in federal tax liability before considering deductions.
Reporting thresholds trigger Form W-2G issuance for certain winnings. Sportsbooks must report winnings of $600 or more when the payout is at least 300 times the wager. Slot machine winnings of $1,200 or more trigger reporting. Poker tournament winnings exceeding $5,000 require withholding and reporting. These thresholds determine when operators must report to the IRS — they don’t determine when income becomes taxable. Winnings below thresholds remain fully taxable; you’re simply less likely to receive paperwork documenting them.
Withholding applies to some gambling winnings. When thresholds trigger W-2G reporting, operators may withhold 24% for federal taxes. This withholding represents an estimated payment against your final liability; depending on your total income and deductions, you might owe more or receive refunds when filing.
Deducting Gambling Losses
Federal tax law permits deducting gambling losses against gambling winnings, potentially reducing or eliminating tax liability on your gambling income. However, this deduction carries specific limitations that prevent using gambling losses to reduce tax on non-gambling income.
Gambling losses can only be deducted up to the amount of gambling winnings. If you won $5,000 and lost $8,000 during the year, you can deduct $5,000 in losses, reducing your gambling income to zero. The remaining $3,000 in losses provides no tax benefit — you can’t deduct it against wages, investment income, or other earnings.
Claiming gambling losses requires itemizing deductions on Schedule A rather than taking the standard deduction. For many taxpayers, the standard deduction exceeds their total itemizable deductions, making the gambling loss deduction inaccessible. If your total itemized deductions — including gambling losses, state taxes, mortgage interest, and charitable contributions — don’t exceed the standard deduction, you’ll likely take the standard deduction and forfeit the ability to deduct gambling losses.
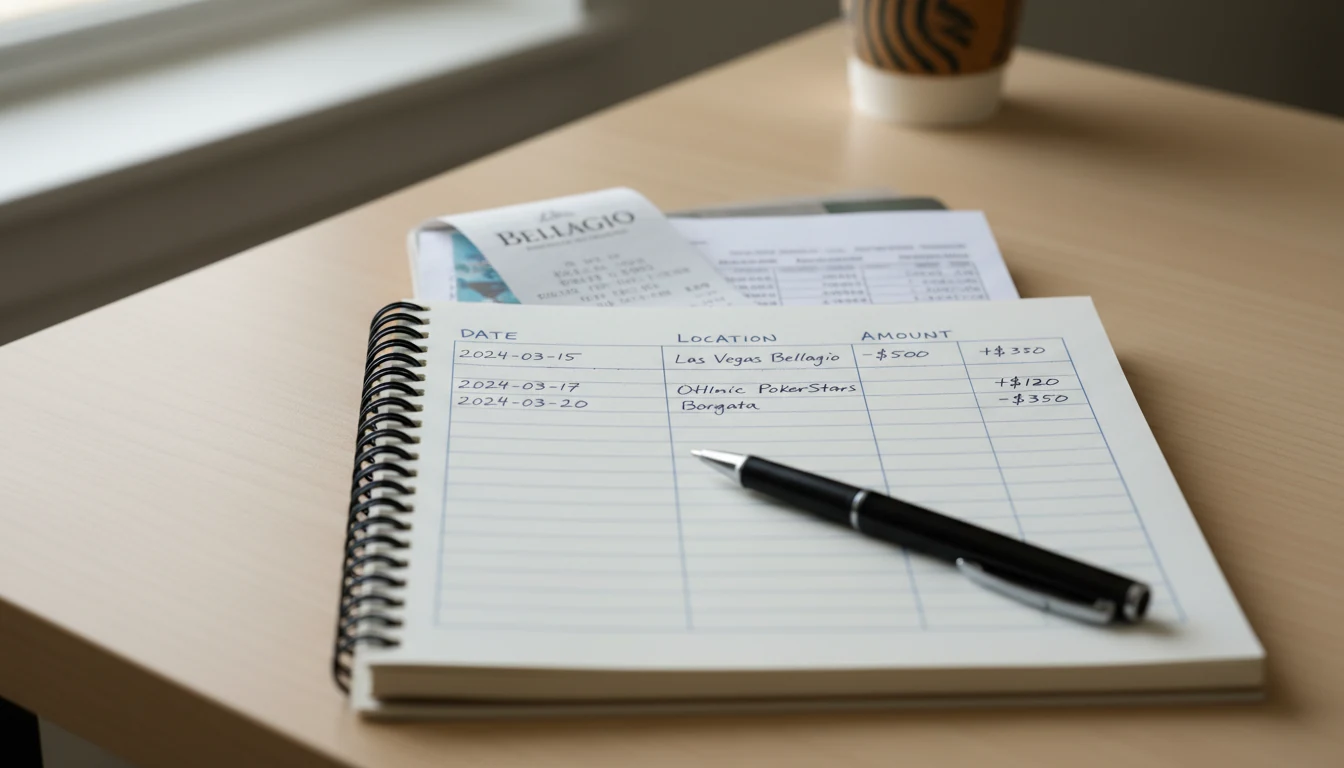
Documentation requirements for loss deductions are substantial. The IRS requires contemporaneous records showing the date and type of gambling, the name and location of the establishment, the amount won and lost, and the names of others present. Reconstructing gambling history at tax time doesn’t satisfy these requirements; proper documentation must be created when gambling occurs.
Record-Keeping Best Practices
Maintaining thorough gambling records protects you during audits and maximizes legitimate deductions. The burden of proof for claimed losses falls on you; inadequate documentation can result in denied deductions and additional tax liability.
Keep a gambling log or diary recording every session. Include dates, locations, types of gambling, duration of play, and net results. For sports betting, record individual bets with outcomes; for casino sessions, record buy-in and cash-out amounts. Digital spreadsheets work well, though handwritten contemporaneous notes also satisfy requirements.
Save supporting documentation beyond your personal logs. Keep W-2G forms, account statements from casino sportsbook platforms, credit card records showing gambling transactions, and any other third-party documentation of your gambling activity. Platform transaction histories often provide detailed records that support your claimed results.
Many casino sportsbook platforms provide annual statements summarizing your activity. Download and save these reports for tax preparation and potential audit defense. The platforms’ records might differ from your personal tracking due to bonus structures, pending bets at year-end, or other timing differences — understand and reconcile any discrepancies.
Retain gambling records for at least three years after filing the relevant tax return. The IRS generally has three years to audit returns, though this extends to six years if substantial underreporting is suspected and has no limit in cases of fraud. Keeping records longer than minimally required provides protection against extended audit periods.
State Tax Considerations
State income tax treatment of gambling winnings varies significantly across jurisdictions. Some states follow federal treatment closely; others impose different rules, rates, or limitations. Understanding your state’s specific requirements prevents unpleasant surprises.
Most states with income taxes treat gambling winnings as taxable income, though rates and brackets differ. Your winnings might face 3% state tax in one state and 10% in another, creating substantially different after-tax results for identical wins.
Some states that permit gambling don’t impose state income tax at all. Nevada, Florida, and Texas — all states with legal sports betting — have no state income tax, meaning gambling winnings face only federal taxation for residents. This creates tax advantages for gamblers in these states compared to those in high-tax states like New York or California (where gambling isn’t legal anyway).
State treatment of gambling loss deductions doesn’t always mirror federal treatment. Some states limit or disallow gambling loss deductions even when federal returns claim them. Check your specific state’s tax laws rather than assuming state treatment follows federal.
Multi-state gambling creates complexity. If you’re a New York resident who gambles in New Jersey, you might face tax obligations in both states. Most states provide credits for taxes paid to other states on the same income, but navigating multi-state situations often benefits from professional guidance.
Use reliable casino digital wallets.
Professional Gambler Considerations
The IRS distinguishes recreational gamblers from professional gamblers, with different tax treatment applying to each category. Professional gambler status offers potential advantages but also carries requirements and risks that make it inappropriate for most players.
Professional gamblers report gambling income and expenses on Schedule C as self-employment income rather than as miscellaneous income with itemized loss deductions. This allows deducting gambling-related expenses — travel, publications, equipment — beyond just losses. It also allows net losses to offset other income, eliminating the limitation recreational gamblers face.
However, professional gambler status triggers self-employment tax on net gambling income and invites substantially higher audit scrutiny. The IRS challenges professional gambler claims regularly, requiring demonstration that gambling constitutes a trade or business conducted with continuity, regularity, and profit motive. Recreational players who gamble occasionally shouldn’t claim professional status regardless of how seriously they approach their gambling.
Factors supporting professional status include gambling as a primary income source, regular and systematic gambling activity, records maintained like a business, and expertise developed through study and experience. Occasional recreational gambling — even if profitable — doesn’t qualify.
Reporting and Compliance
Report all gambling income on your federal return regardless of whether you received W-2G forms. Income remains taxable whether or not it’s reported to you; failing to report income documented on W-2G forms virtually guarantees IRS attention since they already have records of those winnings.
Gambling winnings appear on Form 1040 Line 8, “Other Income,” or on Schedule 1 depending on the return version. W-2G amounts should match what you report; discrepancies trigger automatic notices.
If claiming gambling loss deductions, itemize using Schedule A and include losses on the “Other Itemized Deductions” line. Be prepared to substantiate claimed losses with the documentation described above; the IRS frequently challenges gambling loss claims during audits.
Consider professional tax assistance if your gambling activity is substantial or complex. Tax professionals experienced with gambling income understand the specific rules, documentation requirements, and audit risks. Their fees often pay for themselves through optimized reporting and reduced audit exposure.
Payment of gambling taxes shouldn’t wait until filing. If your withholding from employment and other sources doesn’t cover the additional liability from gambling income, you might owe estimated taxes quarterly. Underpayment penalties apply when too little tax is paid throughout the year, not just when returns are filed.
Master the odds perfectly at top casino sports book.
